Payment Term Negotiation Tools and Tactics for B2B Finance Teams
Secure better payment terms by quantifying cash costs and building defensible negotiating positions.
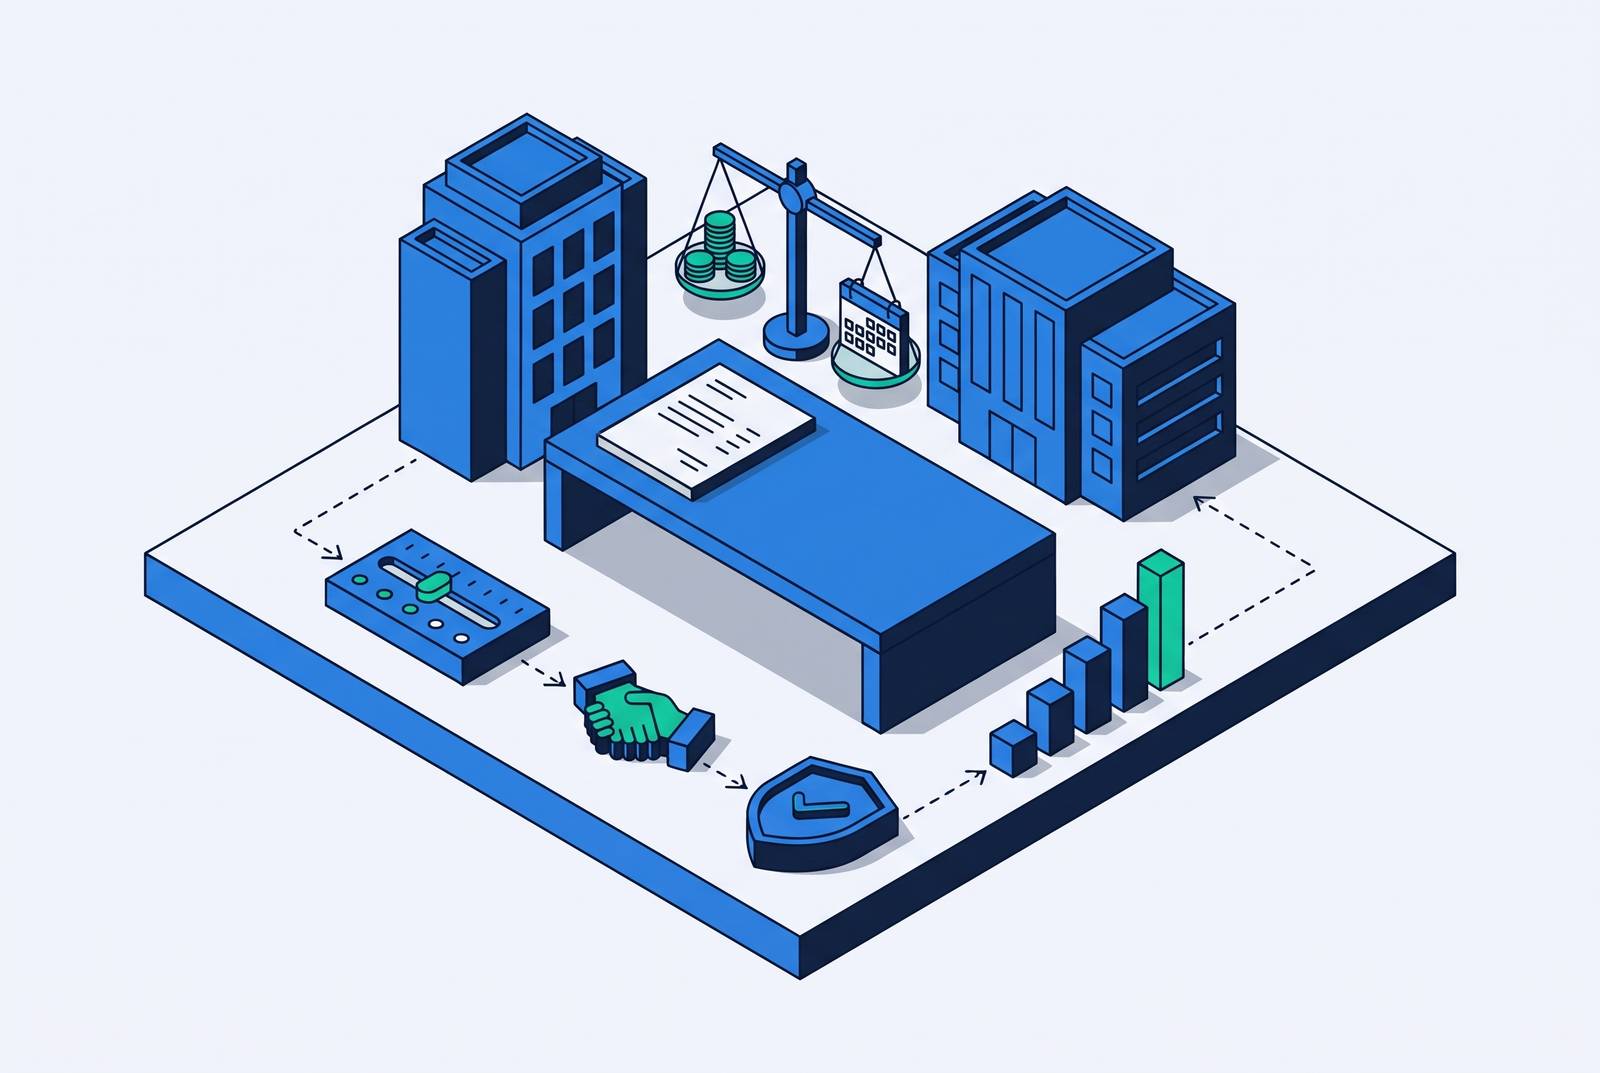
B2B payment term negotiation is a working capital exercise. The strongest finance teams work out what each concession costs, have fallbacks they can defend, and get something useful for what they give up. This keeps cash in the business without forcing customers and suppliers to act as lenders. This guide explains the contract mechanics, negotiating tools, and operational follow-through that make it work.
Why payment terms are a working capital decision, not a contract formality
Terms for customers affect Days Sales Outstanding, while terms for suppliers affect Days Payable Outstanding. Most mid-market companies sit on both sides, so the spread between collections and payments shapes how much cash stays tied up in operations. Net 30 is a lending arrangement with implicit interest and credit risk, even if nobody hands over a loan application.
PwC’s Working Capital Study 25/26 found that Days Sales Outstanding has risen globally over the past decade, while large companies have largely protected their working capital by pushing DPO higher at suppliers’ expense. That creates a structural conflict. Extending supplier terms while tightening customer terms improves one company’s position by putting pressure on another’s. Before negotiating a major contract, finance should work out the cash cost of each extra block of days. That cost gives the team a basis for judging concessions, rather than mistaking a tidy-looking net number for a good deal.
The mechanics inside a payment terms clause that actually drive cash exposure
The headline net period can hide more than it reveals. A useful contract triage starts with four surrounding mechanics, namely the trigger date, late-payment interest and its accrual basis, the disputed-invoice process, and the supplier’s right to suspend. These provisions determine when the obligation starts and what happens when payment stalls. The clock needs a clear starting gun. On Net 30, an undefined “acceptance” trigger can move the real due date by a week or more compared with the invoice date.
The dispute clause deserves equally close attention. A buyer allowed to withhold an entire invoice indefinitely over any objection effectively controls its own payment window. The clause should set a deadline for giving notice, require buyers to pay undisputed amounts on time, and set a fixed window for resolving the dispute. For interest, compounding or a rate untethered to actual harm warrants escalation. The distinction is between compensation and a penalty structure that needs closer scrutiny.
Discount wording can conceal a different kind of exposure. An early-payment discount cuts the price by a small percentage if the buyer pays within a short window ahead of the normal net period. A discount demanded without a reciprocal term concession, or applied retroactively, is a price cut wearing a payment-terms badge.
Preparing a three-position negotiating structure before the conversation starts
Document three positions for each material clause before the discussion begins, which are the ask, the fallback, and the walk-away. Having only one position leaves the team unable to distinguish a genuine impasse from a tactical pause and invites different colleagues to concede different things. A written ladder gives everyone the same basis for movement.
For a supplier, the ask might combine a short net period, market-rate simple interest, and a defined dispute notice window. The fallback could be Net 45–60 in exchange for a tight disputed-invoice process and guaranteed ACH payment. The walk-away could be Net 90 or longer, or any compounding interest structure, with these positions serving as prepared boundaries that can vary by account. Their value comes from deciding them before commercial pressure enters the room.
The best alternative to a negotiated agreement, or BATNA, sets how firmly the team can hold those boundaries. An alternative supplier, a negotiated factoring facility, or an early-payment discount changes the pressure a team can absorb. External criteria strengthen the position further. France’s 60-day cap, sector norms, and the buyer’s stated payment history give both sides facts to work from, while the pending UK cap calls for care to separate proposed law from law already passed. A team that has no real alternative is mostly acting when it says it will walk away.
How to move the counterparty without giving up more than the concession is worth
Every concession should get something in return that is worth what the requested change costs in cash. A blunt move from Net 30 to Net 60 offers the supplier little reason to agree. Firm quarterly orders or promises to buy a set volume can instead help the supplier see what revenue to expect, while guaranteed on-time ACH or card payment helps with processing risk. The exchange needs two sides to work.
Sequence is part of the tactic. Opening beyond the real ask, then allowing silence, can uncover what the counterparty actually objects to. The industrial SME example illustrates how perceived default risk can block an extension more than the net period itself, making a volume commitment or deposit a more useful response than another argument about days. The mirror technique reflects the concern back, while a calibrated question moves the discussion toward a solution. “What would make Net 60 acceptable to your finance team?” asks the counterparty to name the trade.
BCG’s research shows that suppliers asked to wait longer than industry norms may make up for it by raising prices. Additional float can cost more through price inflation than it releases in working capital. Faster payment in exchange for capped price escalation, or access to an early-payment program, can create a better bargain than an unsupported demand for more days.
Credit risk segmentation as the mechanism for setting terms before negotiation begins
A tiered credit policy makes negotiating positions defensible before sales pressure arrives. Rather than deciding every request from scratch, finance assigns available terms by buyer risk category. New buyers can begin on cash-in-advance or Net 15, then graduate to Net 30 and Net 45 as reliable payment behavior builds on the trust of a handshake. This reduces first-order default exposure without permanently restricting good customers.
The assessment needs four inputs, including external bureau data, internal payment history, industry and segment risk, and account size and concentration. Data from outside the business includes commercial credit scores, trade payment history, public filings, and lien searches. Internal records add average days-to-pay and prior delinquencies on the seller’s own invoices. Sector default rates and cyclicality supply context, because a construction buyer has a different baseline risk from a pharmaceutical distributor. Larger accounts warrant deeper review, with a practical mid-market rule that no single buyer should represent more than 10–15% of total receivables.
The output should be a menu of terms. Sales then knows which terms it can offer to buyers in each category before it closes the deal. Finance can check how well that policy works by tracking DSO, Collection Effectiveness Index, bad debt as a percentage of revenue, and changes in risk scores across the portfolio. Rising DSO with unchanged terms signals a need to recalibrate segmentation.
Early-payment programs as a negotiated working capital tool for both sides
The choice between dynamic discounting and supply chain finance starts with the buyer’s cash position. Does it have surplus cash to invest, or does it want to conserve cash while helping suppliers obtain cheaper funding? The funding source is the dividing line. Dynamic discounting uses the buyer’s own cash to pay approved invoices early in exchange for a sliding-scale discount. The reduction is larger for earlier payment, smaller further out, and disappears at the contracted net date.
With supply chain finance, also called reverse factoring, a bank or third-party funder pays suppliers early on the strength of the buyer’s credit. The buyer can extend DPO without deploying its own cash, while suppliers obtain cheaper funding than their own credit rating would provide independently. Some buyers combine the two approaches. They use their cash in the earliest days after approval, then bank funding outside that window. J.P. Morgan’s Working Capital Accelerator Platform lets buyers switch between the two in near-real-time.
A modest discount within a short accelerated window is worthwhile only when it costs less than holding the receivable plus the administrative expense of collection. Otherwise, the seller is subsidizing the buyer’s float.
The accounting and disclosure obligations that supply chain finance creates
Programs used chiefly to extend DPO without proper disclosure create audit and reputational risk, because investors and regulators treat undisclosed SCF-funded payables as disguised debt. The funding may help both commercial parties. That does not settle how the resulting obligation should appear in the accounts.
Carillion provides the concrete warning. The UK construction and facilities management company collapsed in 2018 after burying nearly £498 million in bank liabilities within its supply chain finance programme, misclassified as “other creditors”. Its collapse made opacity around these arrangements a regulatory trigger.
IASB amendments to IAS 7 and IFRS 7 require qualitative and quantitative disclosures about supplier finance arrangements for financial years beginning 1 January 2024. Those disclosures let investors assess effects on liabilities, cash flows, and liquidity risk. Auditors should therefore be involved before launch and before the structure has been agreed. Whether funded payables should be reclassified from trade payables to debt is a material judgment. It is not an administrative tidying-up exercise.
How real-time payment infrastructure and new regulation are changing the terms that are possible
Faster payment rails make payment float less useful, while regulation can rule out longer terms altogether. Both developments change which fallback positions finance can credibly defend. Payment speed also brings security into the discussion. AFP’s 2026 Payments Fraud and Control Survey found significant attempted or actual payments fraud among US organizations in 2025, with checks most targeted, followed by ACH debits and wires. When the parties agree to change the payment method, they should also spell out the fraud controls that go with it.
The UK Commercial Payments Bill 2026 would introduce a 60-day cap for large firms paying SME suppliers, with an exemption where both parties are large businesses. Presented to Parliament on 19 May 2026, it has completed its Lords stages, with third reading on 20 October 2026, and is expected to move to the House of Commons. It has not yet passed. The government expects the cap to take effect no earlier than 2027.
For in-scope relationships, the Bill would void contractual terms extending payment beyond 60 days and mandate late-payment interest above the Bank of England base rate. It would also allow the Small Business Commissioner to impose turnover-based financial penalties for persistent late payment. Whether the turnover basis would be UK-only or worldwide remains subject to consultation. Finance teams should treat this as a constraint on future negotiating options.
Turning agreed terms into cash: the operational gap between a signed contract and a paid invoice
A signed clause does not chase an invoice. Even Net 30 backed by interest provisions and a tight dispute process can produce late payment when follow-up and escalation are absent. Missing W-9s, invoices buried in Coupa or Ariba, unanswered dispute notices, and stalled approval chains can all block cash after the commercial argument is settled.
The operational response combines sequenced follow-up, active portal navigation, and escalation that distinguishes collection problems from disputes. Automated outreach should mirror a human AR team’s cadence and match the communication style the customer responds to. Portal work means pushing invoices through the customer’s process on its timeline. Escalation then routes unresolved disputes toward resolution rather than treating every delay as a need for another payment nudge.
Finance should use AR to enforce negotiated terms by checking that customers meet the agreed trigger dates, dispute windows, and payment commitments. The negotiation establishes what the company is owed and when. Persistent execution turns that entitlement into cash in the bank.