AI Agents versus Traditional Finance Automation
AI agents handle messy invoices and exceptions where rule-based automation simply stops.
An invoice lands in a finance team's inbox. Nobody's seen the format before: maybe it's a scanned PDF with the line items in a weird order, maybe it's missing a PO number that normally lives in a specific field. Traditional automation looks at that invoice and stalls, because there's no rule written for "field is blank and the format is unfamiliar." An AI agent looks at the same invoice and does what a competent new hire would do: reads it, figures out what's missing, checks the vendor's history, and either fills the gap or asks someone a specific question. That's the whole article in one example.
The real difference between traditional automation and AI agents is whether the tool can interpret context or whether it can only execute a fixed instruction. Robotic process automation, RPA, runs on deterministic logic: if this field equals X, copy it to Y. That works fine when inputs are stable, formats never change, and nobody has to use judgment. It has no model of context built in, so it follows instructions literally even when those instructions have stopped making sense for the situation in front of it.
AI agents operate differently at a structural level. They perceive data, weigh multiple variables against each other, and take action toward a goal, which puts them in a different category from both RPA and chatbots. Chatbots answer questions and stop there, at the edge of the conversation. Agents chain tasks across systems, taking the output of one step and feeding it into the next. And when conditions change, the two tools respond in opposite directions: agents adapt, RPA breaks.
None of this means every finance workflow needs a fully autonomous agent that makes decisions with no human in the loop. Most enterprise deployments headed into 2026 blend modes depending on the stakes involved. Humans set the parameters and audit the outcomes. Nobody's handing the keys to the building over on day one.
Where RPA breaks down in finance operations
RPA isn't a failure of ambition. It was built to do one job well: repeat a fixed set of steps on structured inputs, fast and tirelessly. The trouble is that finance operations are running out of workflows that stay inside those lines, and the workflows still stuck in manual labor are stuck there because they never fit the tool.
Start with the mechanics. Teams then spend hours on maintenance work fixing a process that was supposed to run itself, which is a strange way to spend the time automation was meant to save.
Unstructured data makes the problem worse, as the default condition of financial paperwork rather than an occasional edge case. Invoices, purchase orders, and vendor correspondence rarely arrive in one consistent format, and RPA halts completely the moment it meets an exception: a missing field, conflicting numbers, a layout it hasn't seen before. The team ends up managing bots instead of doing the higher-value work the bots were supposed to free them up for.
The cost of all this appears less in licensing fees and more in upkeep hours. And because bots interact with each other across systems, if one reconciliation bot breaks, it can stall month-end close for an entire company, which shows a tool built for a narrower job than the one finance now needs done.
What AI agents can do that rule-based tools cannot
The case for agents comes down to one capability: resolving exceptions, which is the exact point where rule-based systems give up. Agents also read the unstructured material, the PDFs and emails and handwritten notes, that RPA was never built to parse.
Picture an accounts payable discrepancy. An agentic system does more legwork before it bothers a human. It pulls up the original PO, checks the contract terms, looks at the vendor's billing history, and if the discrepancy falls inside an agreed tolerance, it approves the invoice on its own. If the discrepancy doesn't fit that pattern, it contacts the vendor with a specific question about the mismatch and waits for an answer before routing anything to a person. Each step gets logged, so the reasoning behind the decision is something a human can actually review later rather than a black box producing a verdict with no paper trail. That multi-step chain of action across systems, inside one workflow, is what separates an agent from an ordinary AI assistant that just answers a question and stops.
Combining large language models with retrieval-augmented generation lets agents work across contracts, scanned invoices, and handwritten notes alongside the clean, structured data sitting in an ERP system, something screen-scraping bots can't touch. That matters for working capital too. Rule-based tools can't do that kind of portfolio-wide reasoning because they handle one task at a time, in isolation, with no sense of the bigger picture.
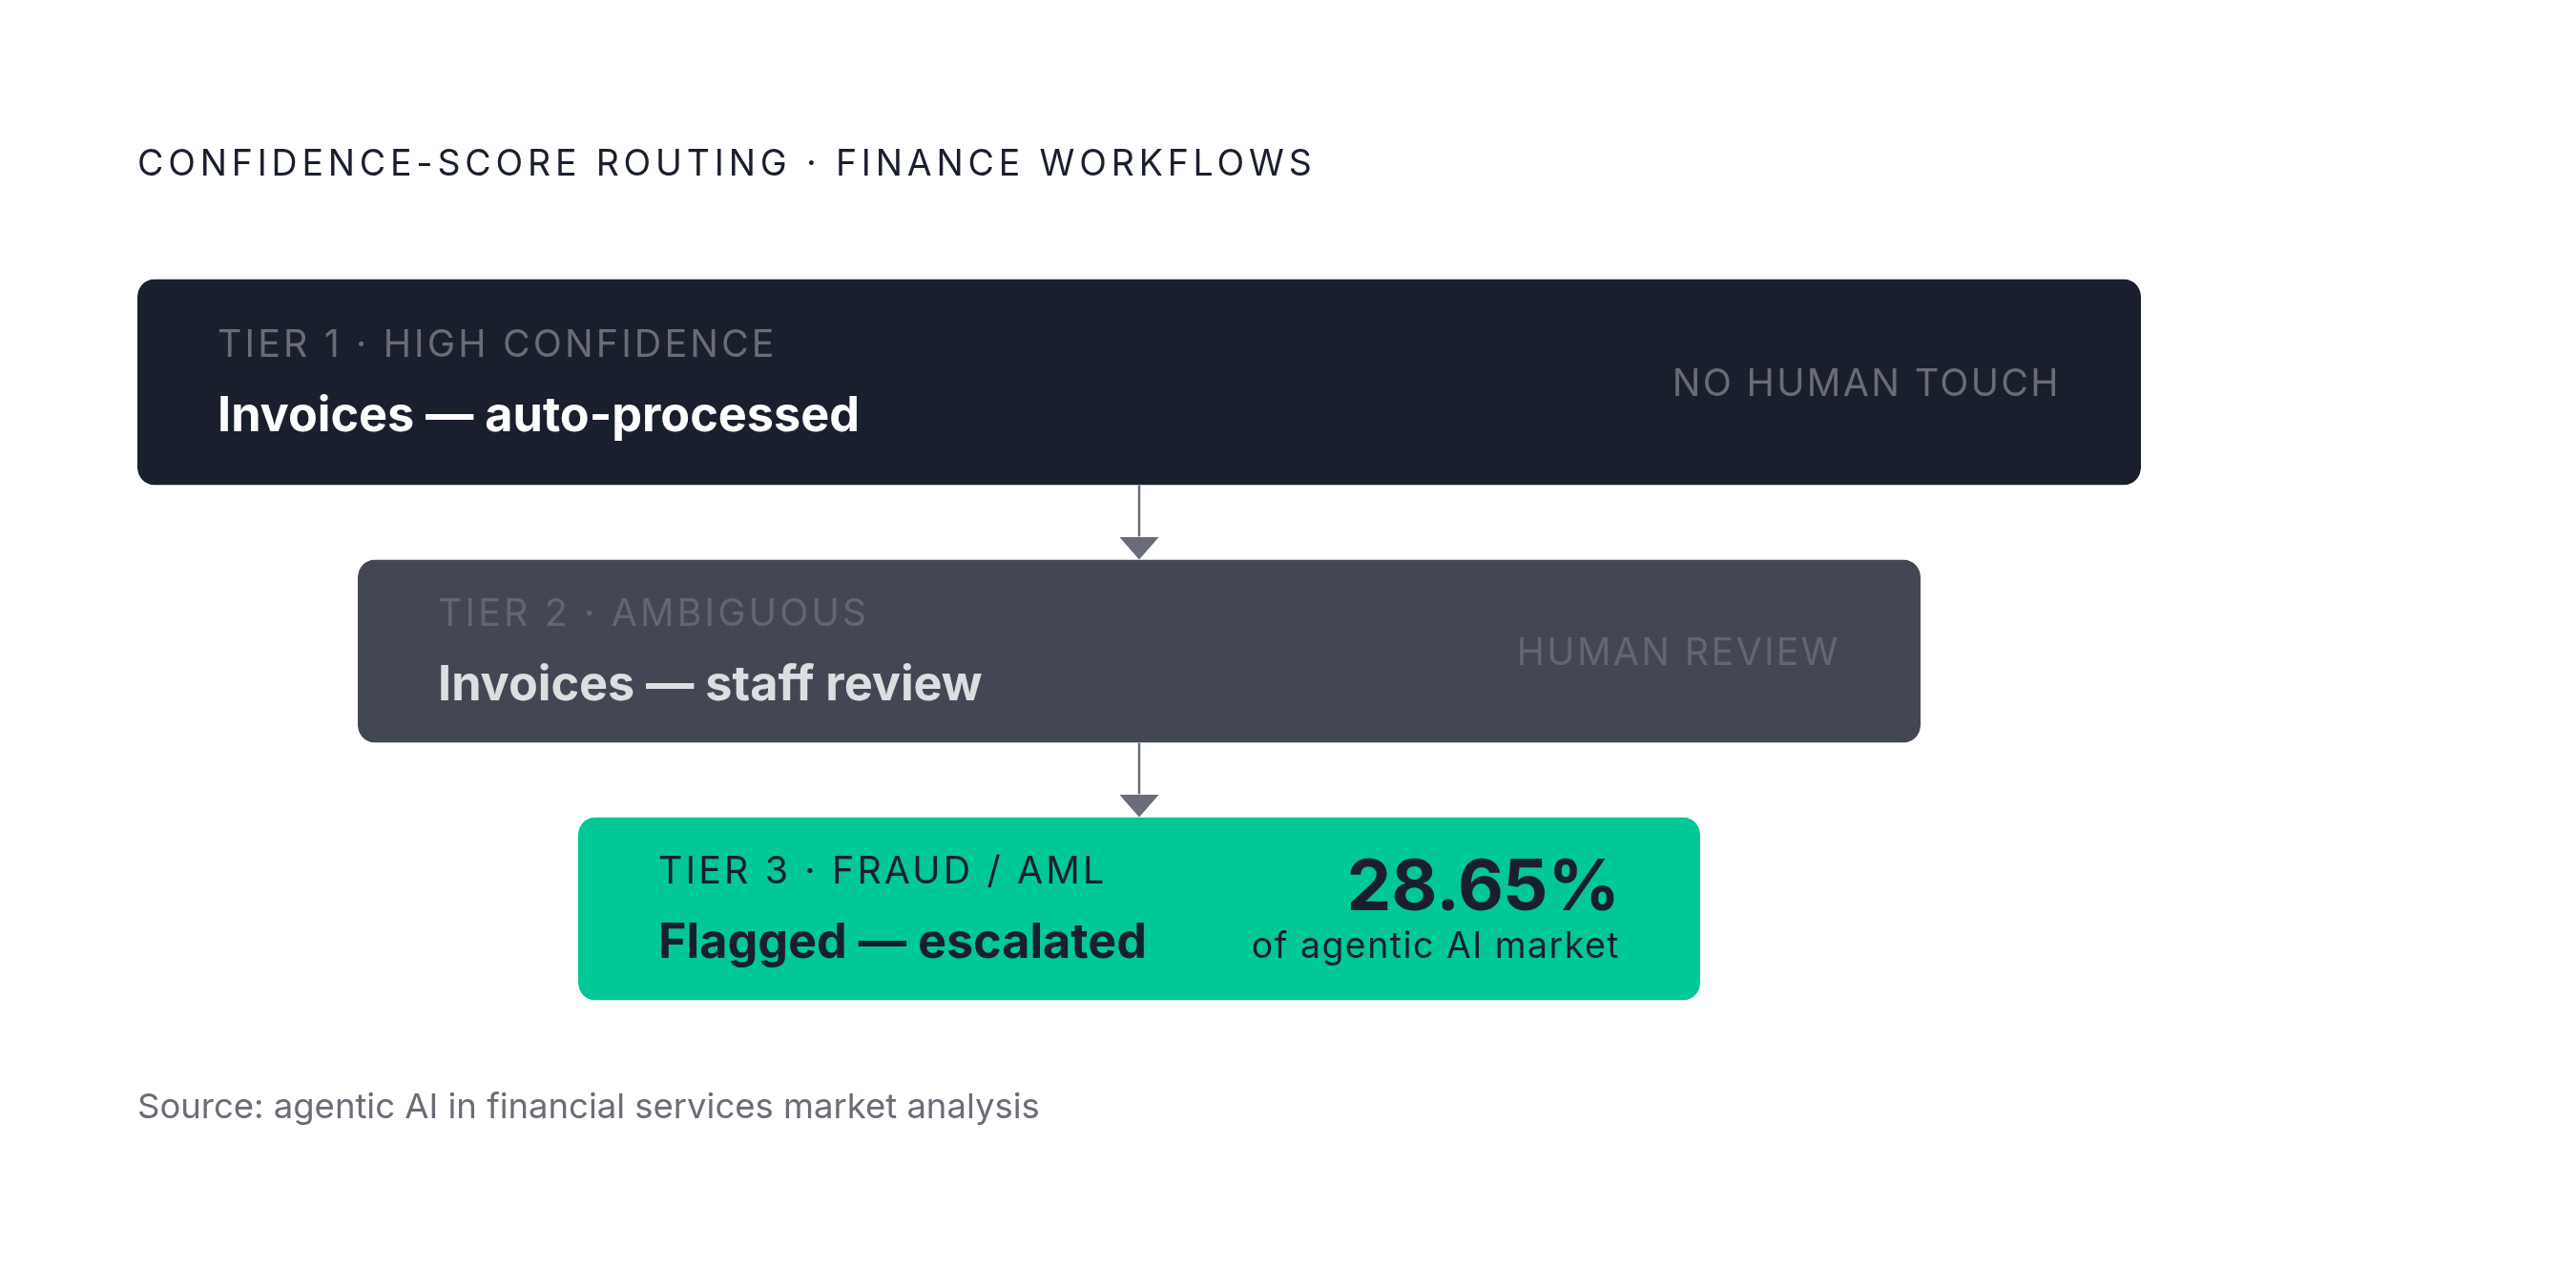
Agents also tend to get better with use. The version of the agent handling a Q2 close produces sharper results than the one that handled Q1, without anyone rewriting its rules in between. Fraud detection and anti-money-laundering work alone make up 28.65% of the agentic AI market in financial services, which gives some sense of how much weight this one capability is already carrying.
Where agents deliver real results in production
The theory holds up in practice, but the gains cluster around specific kinds of workflows, so they don't spread evenly across every corner of finance. High-volume, exception-heavy, unstructured work benefits the most, and that tracks with everything you just read.
HPE's CFO, Marie Myers, told CFO Dive in February 2026 that her team is scaling its internal agentic AI tool to cover credit, collections, accounts payable, and receivable processing, building on a pilot that ran through 2025. That's one of the more senior, on-the-record confirmations that agentic finance work has moved past the experimental stage and into daily operations at a large company.
Genpact reported results from a client in global food services, where the company processes millions of invoices a year. After deploying Genpact AP Capture, the company's agentic accounts payable tool, invoice processing time dropped sharply, and the rate of invoices posting automatically, without a person touching them, rose substantially. The gain traces back to one specific capability: the agent's ability to handle format variation in incoming invoices that used to require someone to step in by hand.
A pattern is starting to repeat across these deployments. High-confidence invoices move through the system untouched by a human. The agent assigns each invoice a confidence score, and only the genuinely ambiguous ones get routed to a staff member. That's how a finance team can process a much larger volume of invoices without adding headcount to match. Graybar's CFO, David Meyer, has pointed to working capital benefits his company has already seen from this kind of work and described plans to expand the use of data analytics, machine learning, and AI to sharpen forecasting, manage inventory, and improve cash flow.
The scale of adoption backs this up at a market level. Forrester's 2026 predictions estimate that roughly a third of B2B transactions this year will involve autonomous agents that manage invoicing, reconciliation, or spend control. Gartner predicts that 40% of enterprise applications will be integrated with task-specific AI agents by the end of 2026. Production deployment at this point is a normal part of how a growing number of finance departments operate.
AR and collections in this shift
Most of the published examples so far sit on the accounts payable side. Accounts receivable tells a related but different story, and it's where the limits of rule-based tools are easiest to see.
Invoices in AR rarely stall because data is missing from a database somewhere. They stall because someone has to navigate a supplier's payment portal, track down a missing W-9 form, or chase a communication gap that needs a real, persistent follow-up rather than one more automated reminder email. That's a fundamentally different kind of friction than a mismatched price on an invoice.
AR and AP aren't the same problem wearing different labels. Accounts payable deals with a company's own outgoing payments, inside an environment the company largely controls. Accounts receivable means acting on behalf of the company out in the world of its customers: portals like Coupa and Ariba, inboxes that expect a reply with actual context behind it, escalation decisions that call for judgment about when to push harder and when to hold off. Rule-based automation was built for workflows that are internal and predictable. Supplier portals work the opposite way: layouts change without warning, uploads get required out of nowhere, and status messages show up that don't match anything a script was written to expect. Screen-scraping handles that kind of one-off navigation about as poorly as a tool can.
Closing that gap takes both pieces at once, the reasoning ability of an AI agent and the kind of persistent follow-up that actually gets a response out of a customer. Automation alone doesn't get there, and neither does a person working the phones alone. Invoice Butler's approach to collections illustrates this agent advantage directly: when a supplier sends an invoice by email, text message, or through a portal in a format that doesn't match the usual pattern, the system has to work out vendor history, payment terms, and communication preferences before it can act, exactly the kind of judgment call that stops rule-based RPA cold. It functions less like a piece of software bolted onto a finance stack and more like an always-on AR team, one that follows up, answers customers directly, works through portal logins and document uploads, escalates the cases that need a human, and keeps pushing an invoice until the cash actually lands. Collections and AR follow-up rank among the highest-volume, most exception-heavy jobs in finance, and the fact that they've stayed manual labor through decades of automation tooling says something about how badly deterministic automation fit the job. Invoice Butler's deployment across a large receivables base for fast-growing companies runs at production scale, not as a pilot or a proof of concept, which is the clearest sign that agentic reasoning gets results here where rule-based tools historically couldn't.
The governance gap holding back agent deployment
None of this means finance teams should hand agents the keys and walk away. The biggest barrier to wider agent deployment is whether an organization has built the governance structure needed to let agents act on its behalf on decisions that actually matter.
Deloitte's Finance Trends survey found that a majority of organizations have fully deployed some form of AI, yet only a small fraction have fully integrated AI agents directly into the finance function itself. The gap between those two numbers comes down largely to governance and data controls, because they haven't caught up with how fast deployment has moved.
Hallucinations, model drift, regulatory non-compliance, a lack of explainability, over-automation with no human check, exposed confidential data: these are the concrete failure modes finance leaders have to plan around. The Cambridge Centre for Alternative Finance's Global AI in Financial Services Report found that a majority of regulators surveyed worry about model opacity and a lack of explainability, while a majority of industry respondents worry about losing human oversight. The IMF's 2026 note on agentic AI in payments raises a systemic concern on top of that: when agent behavior is opaque and nonlinear, supervisors struggle to spot systemic risk in time, and if a lot of agents start behaving the same way at once, that correlation becomes its own kind of risk.
Regulation is catching up with all of this. The EU AI Act's deadline for high-risk AI systems is December 2027, and it classifies credit scoring and automated financial decision-making as high-risk uses (fraud detection carries an explicit carve-out from that classification, under Annex III, point 5(b)). Institutions covered by the rule have to show explainability, human oversight, audit readiness, and documented risk management, and the penalties for falling short run up to €35 million or 7% of global annual turnover.
A related problem has picked up a name of its own: agent washing, where a vendor markets a system as production-ready for finance without the governance infrastructure to back that claim up. Gartner projects that more than two-fifths of enterprises will demote or decommission autonomous agents by 2027 after governance gaps surface in production. That number puts a price on what happens when a team deploys ahead of its own readiness.
The migration path practitioners are taking
None of this points toward standing still, and it doesn't point toward switching everything over at once either. The organizations getting real results, HPE, Alphabet, Graybar, Genpact's client, started with one workflow where the exception volume was high and the stakes were manageable, let the agent earn trust on that workflow, and expanded from there. Credit approvals and anything touching regulatory exposure keep a human in the loop as the default, at least for now. Expense categorization, invoice matching on the easy end of the spectrum, and routine AR follow-up are where autonomy gets handed over first, because the downside of a mistake is a correction, not a crisis.
The practical test for any team weighing this is whether the organization can show, after the fact, why the agent did what it did, and whether someone was positioned to catch it if it got something wrong. Build that discipline first; the rest of the migration, AP today, AR and collections not far behind, tends to follow its own momentum.
Sources
- How Agentic AI Will Reshape Payments in: IMF Notes Volume 2026 Issue 004 (2026)
- Top AI Agents for Finance in 2026: Automation, Forecasting & Profitability
- Beyond RPA: AI agents transform finance automation 2026
- 11 Best AI Agents for Financial Services in 2026
- The ultimate guide to AI agents in finance: How FP&A teams are using agentic AI in 2026
- 2026 Global AI in Financial Services Report